No stress, no bureaucracy and total transparency. Simulate now and swap your heavy instalment for a lighter one - without wasting time.
Why simulate your housing credit transfer with us?
|— Save more by saving here
Forget high interest rates. Here, the focus is clear: Reduce your monthly instalment and simplify the entire process, so you can save and spend your money where it really matters.
Simulate credit now
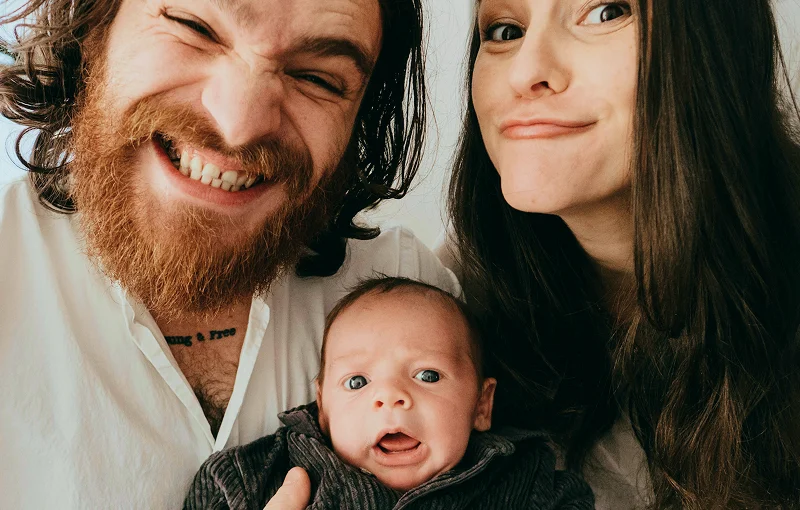
The couple faced financial difficulties, but with our help, they significantly reduced their monthly housing credit instalments with a simple transfer.
Simulate your transfer
The couple was paying an instalment of €1,439.28 per month, with a variable rate indexed to the 12-month Euribor.
At a different bank, they obtained a proposal with a mixed rate – fixed for one year and then variable again.
With the new conditions presented, the couple decided to transfer their housing credit to another bank and started paying a monthly instalment of €1,121.54.
Per month, the couple saved €317.74, and per year, they achieved savings of €3,812.88.
Everything you need to know to build your knowledge before taking the first step towards a new housing credit
eBook on housing credit
If you're thinking of buying a home, this complete guide on housing credit is for you.
Mortgage Credit
Is your spread high? Find out how much more you might be paying
The spread of your housing loan may be above current available conditions. Learn how to assess your spread and...
Mortgage Credit
Effort rate of 45%: how much can you ask to buy a house?
The effort rate is one of the main indicators used by banks when analyzing a housing loan application. Since A...
Mortgage Credit
Bank home evaluation: how it works and why it can be decisive for credit?
The property evaluation is an important step in housing credit. Learn what it is for and what can happen if th...
Mortgage Credit
New housing credit rules: what changes in financing approval?
Know what has changed and what to consider before proceeding with a housing loan.
Mortgage Credit
What happens to housing loan if you lose your job?
We explain what to do in case of income loss, what coverages you can find in the home loan insurance, and what...
Mortgage Credit
Housing loan: pay off or invest? What is more profitable?
Do you have money available and still pay the housing loan? Find out what to consider before deciding between...
Mortgage Credit
Housing Loan: how to sell your current house to buy a new one?
Switching homes while still having a housing loan requires planning. Learn what to analyze before selling your...
Mortgage Credit
Home loan: what happens when the house appraisal is lower than the purchase price?
If the bank valuation is below the purchase price, the financing may be affected. Know what may happen and how...
Mortgage Credit
Do you have a mortgage for several years? 7 things you should review with Poupança no Minuto.
The terms of the home loan may become less competitive over the years. Find out when it might make sense to re...
Mortgage Credit
Housing loan for 30, 35 or 40 years: which term is more advantageous?
30, 35 or 40 years: what is the most advantageous term for your housing loan? Compare the impact on the monthl...
Mortgage Credit
When is 6% or 23% VAT paid in construction?
The cost of a work can vary greatly depending on the VAT rate applied. But when can you benefit from the reduc...
Mortgage Credit
"Poupança no Minuto: Main differences between mortgage and leasing?"
When buying a house, there are several ways to finance the property. Home loans remain the most common option,...
Mortgage Credit
How to read a PIE (European Standardized Information Sheet)
When looking for a loan and banks make tempting offers, only one document reveals the total financial truth. D...
Mortgage Credit
"Poupança no Minuto Housing Credit Guide: Everything You Need to Know"
Buying a house is one of the most important decisions in your financial life. Two bank proposals with the same...
Mortgage Credit
Real estate capital gains in 2026: calculation, exemptions and planning. Poupança no Minuto
Selling a house usually generates a profit and the Tax Office always claims its share. Understanding what capi...
Yes, you can transfer your home loan at any time during the contract. Generally, there are no clauses preventing the borrower from transferring the loan to another bank. However, you must notify your current bank with a minimum of 10 days' notice. After that, the bank has 10 days to provide the loan data and documents to the new bank where the transfer will be made.
To transfer your home loan, you should contact other banks to obtain proposals that suit your needs. After receiving these proposals, compare them with the current conditions of your loan. At Poupança no Minuto, we help mediate the process and identify the most advantageous proposal for you.
The main advantages of transferring a home loan include: Reduction of the spread, resulting in a decrease in the Nominal Annual Rate (TAN); Extension of the contract term; Change of interest rate type (from fixed to variable, or vice versa); Reduction of required insurance premiums; With a new appraisal, the market value of your home may increase.
The APB protocol is an agreement between most banks that allows a mortgage to be transferred from one bank to another. To do this, you must request the Authorization Term at the bank where the mortgage is registered. This term, duly signed and stamped, must be delivered to the bank to which you wish to transfer the loan.
Costs may vary from bank to bank, but the most common include: Early repayment commission (up to 0.5% of the repaid capital if the interest rate is variable, or up to 2% if fixed); New deed costs; Application opening fees; New property appraisal costs.
Talk to an agent now
Want to know more? Talk to one of our agents to clarify any doubts and discover the perfect solution for you.
Call to national landline | Monday to Friday, 9am to 7pm.